A plain-English guide to roof replacement after storm damage: the pros and cons of filing an insurance claim, how to spot damage, and how to choose the right roofing company.
Hail and wind storms roll through Northwest Louisiana and East Texas every year, and many roofs carry damage their owners never noticed. That damage matters when you're living in the home, and it matters even more when you're buying or selling one.
This guide is written for:
We're Indemnity Roofing & Construction, a Louisiana-licensed roofing contractor (License #76747) based in Shreveport. We inspect and replace roofs. We're not your insurance company, and we're not your lawyer. This guide shares general information so you can make informed decisions; your policy and your own advisors have the final word.
Storm damage often goes unnoticed for a long time. Here's what to keep in mind:


Damage that goes past the shingles means repairing the framing and decking before a new roof goes on.
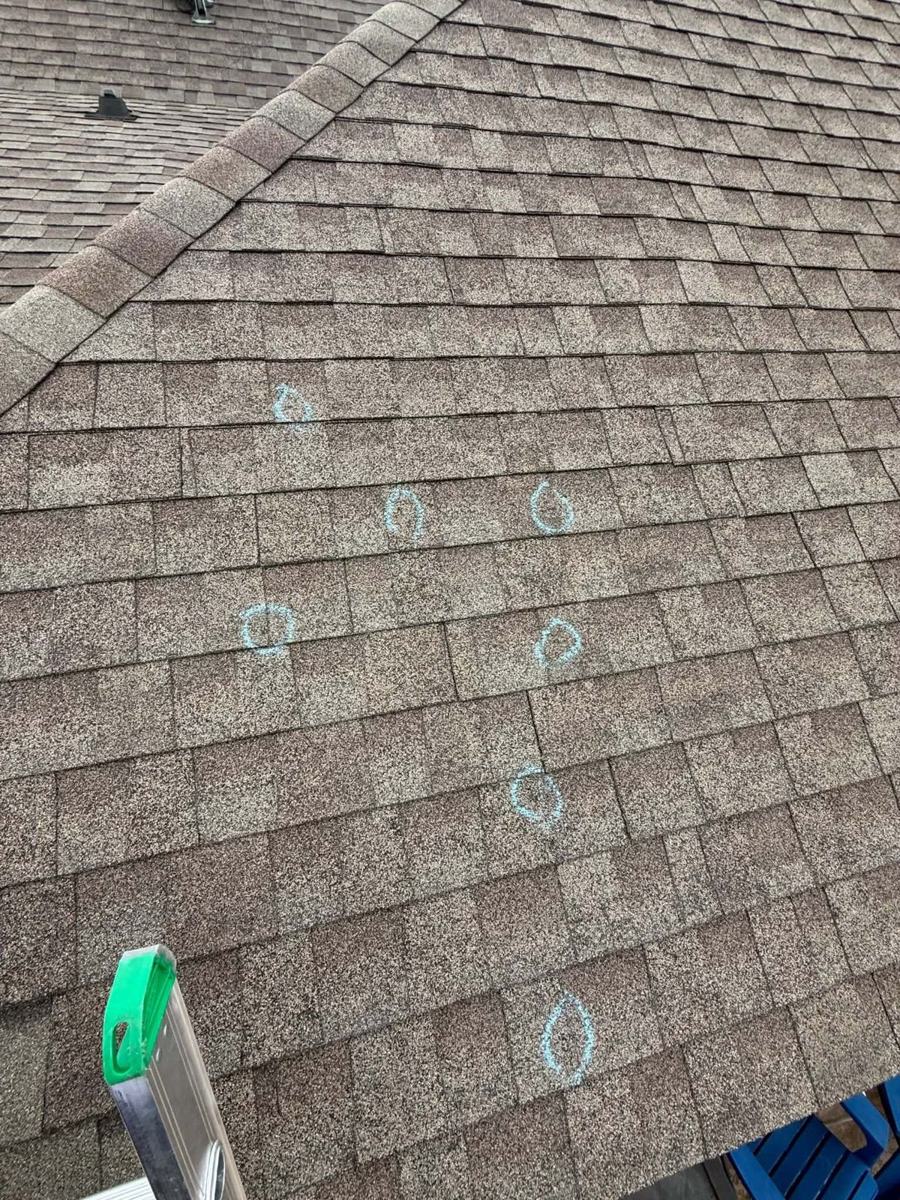
Most storm damage can't be seen from the ground. Watch for these clues:


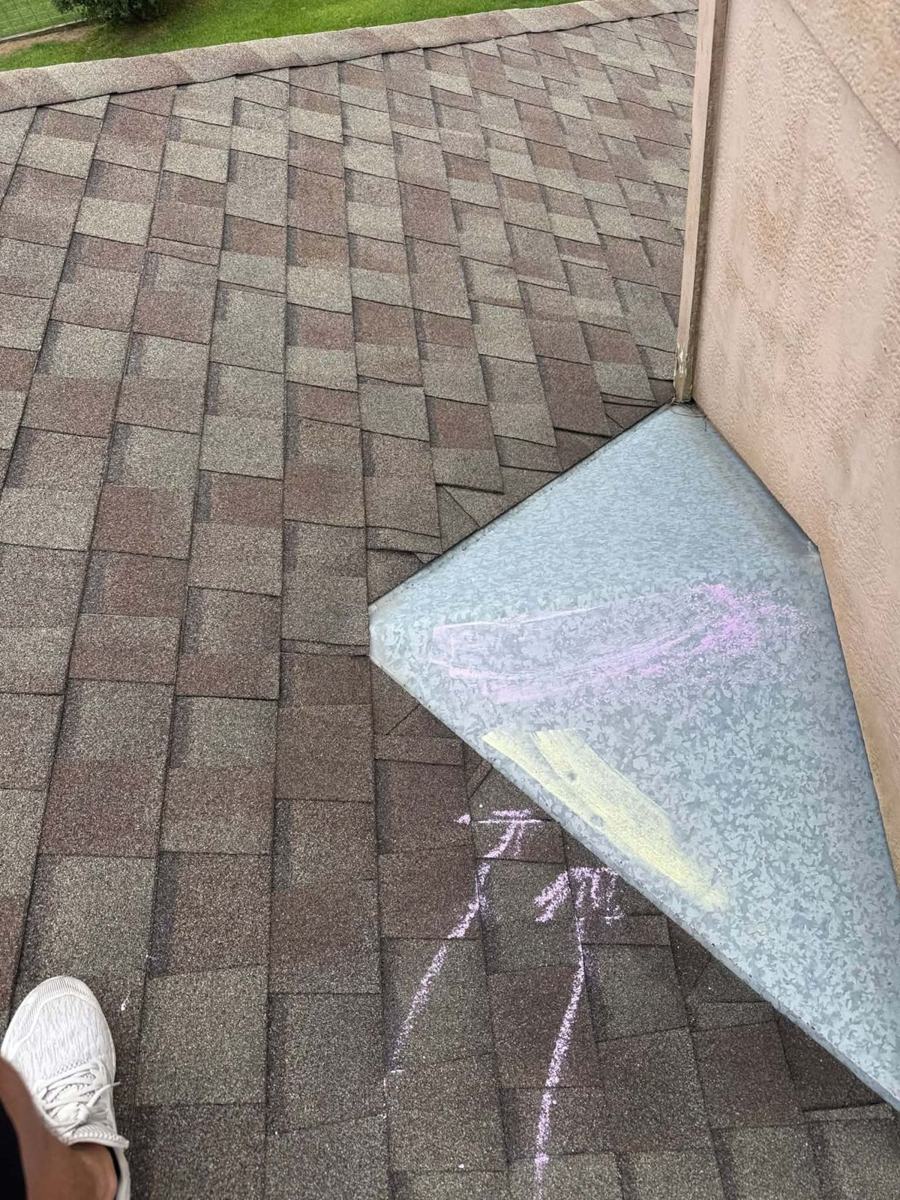
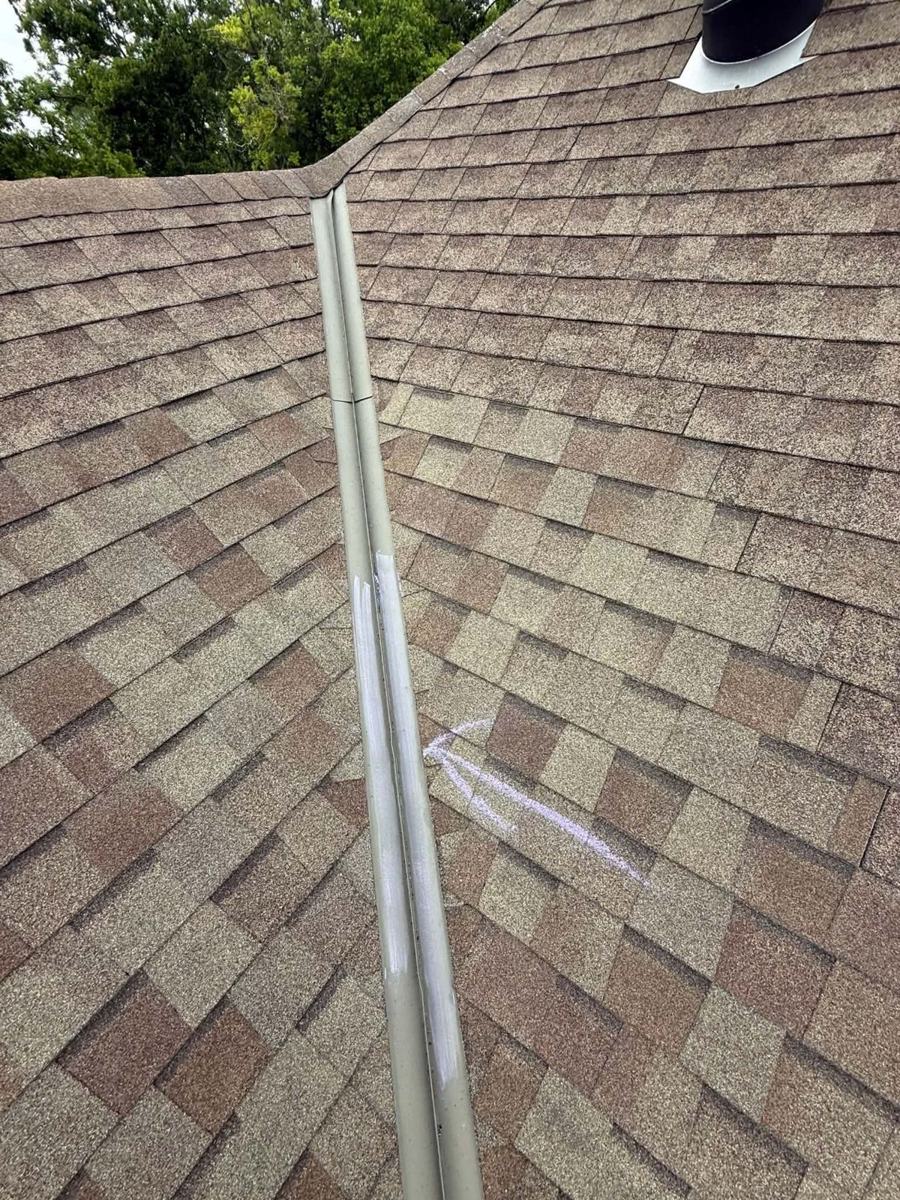
Hail hits circled in chalk during Shreveport inspections: on shingles, flashing, and valley metal. Most of this can't be seen from the ground.
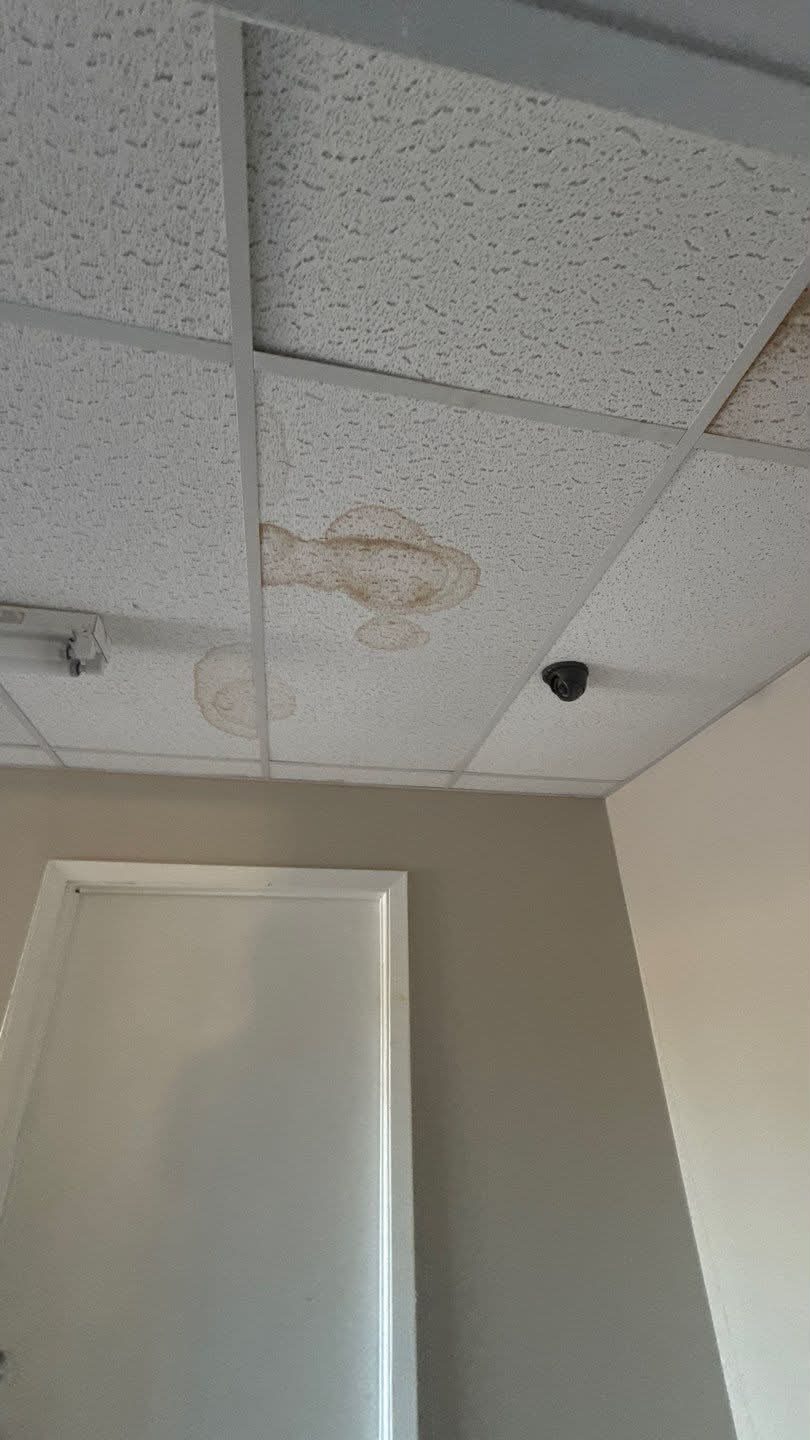
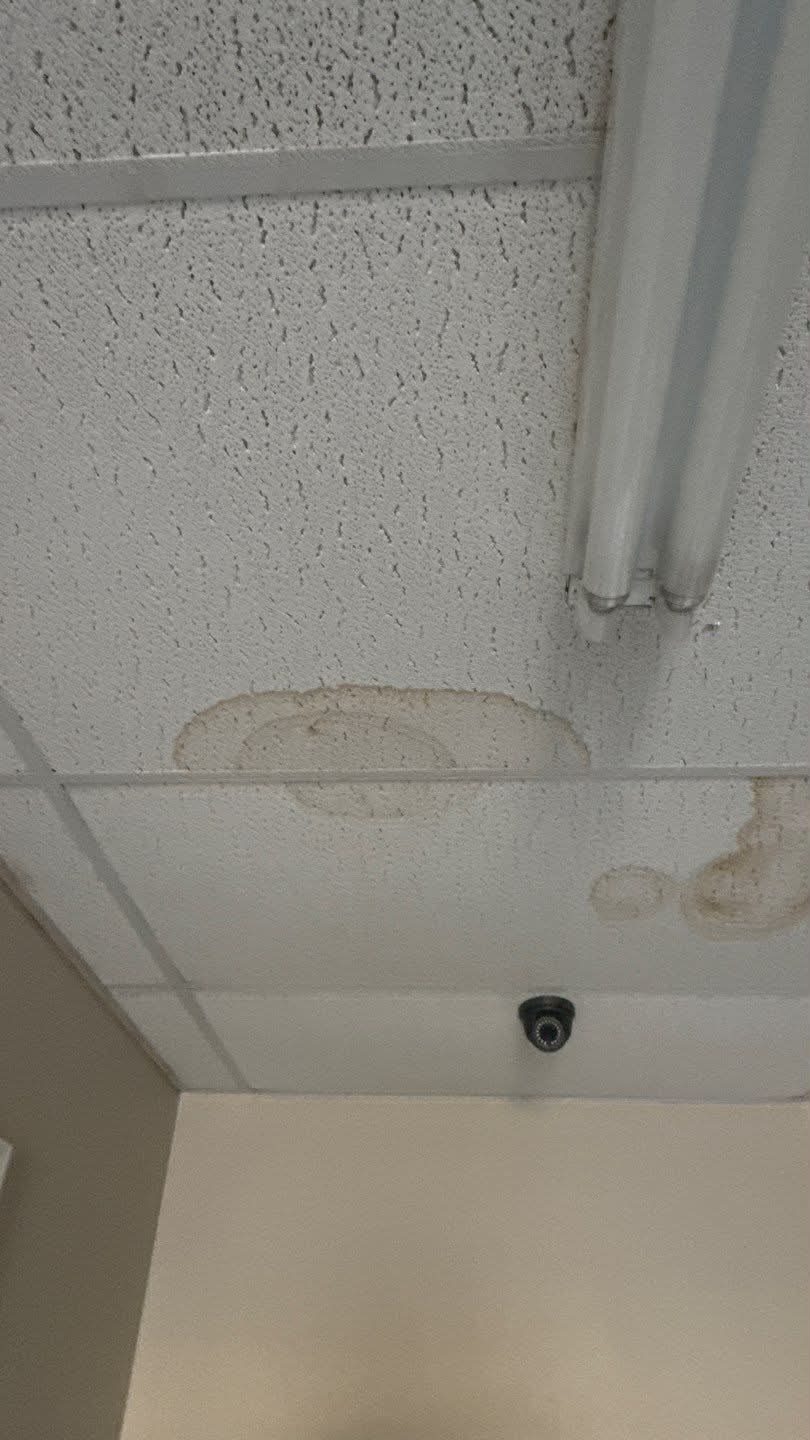
Ceiling stains like these usually mean water has been getting through the roof for a while.
Please don't climb on the roof to look. A free professional inspection is safer and catches what you can't see. Learn more on our hail and storm damage page.
Our advice: get a free inspection first. If there's no real storm damage, you'll know before anything goes on your record. If there is, you'll have photos and documentation ready. Talk with your insurance agent about how a claim could affect your policy.
Knowing who plays which role protects you and keeps everything above board.
| Who | Works for | What they do |
|---|---|---|
| Your insurance company's adjuster | The insurance company | Inspects the damage and decides what the policy pays |
| Your roofing contractor | You, as the customer | Inspects and documents roof damage, provides a repair scope and estimate, meets the adjuster to show the damage, and does the work |
| A licensed public adjuster (optional) | You | Can evaluate and help you with your claim for a fee. Must be licensed, and in Louisiana can't also do the repairs |
| An attorney (optional) | You | Can advise you and represent you if a claim is wrongly denied or underpaid |
A reputable roofer documents the roof and stands behind its own estimate, but it shouldn't tell you what your policy covers or negotiate your claim for you. If a roofer promises that, be cautious.
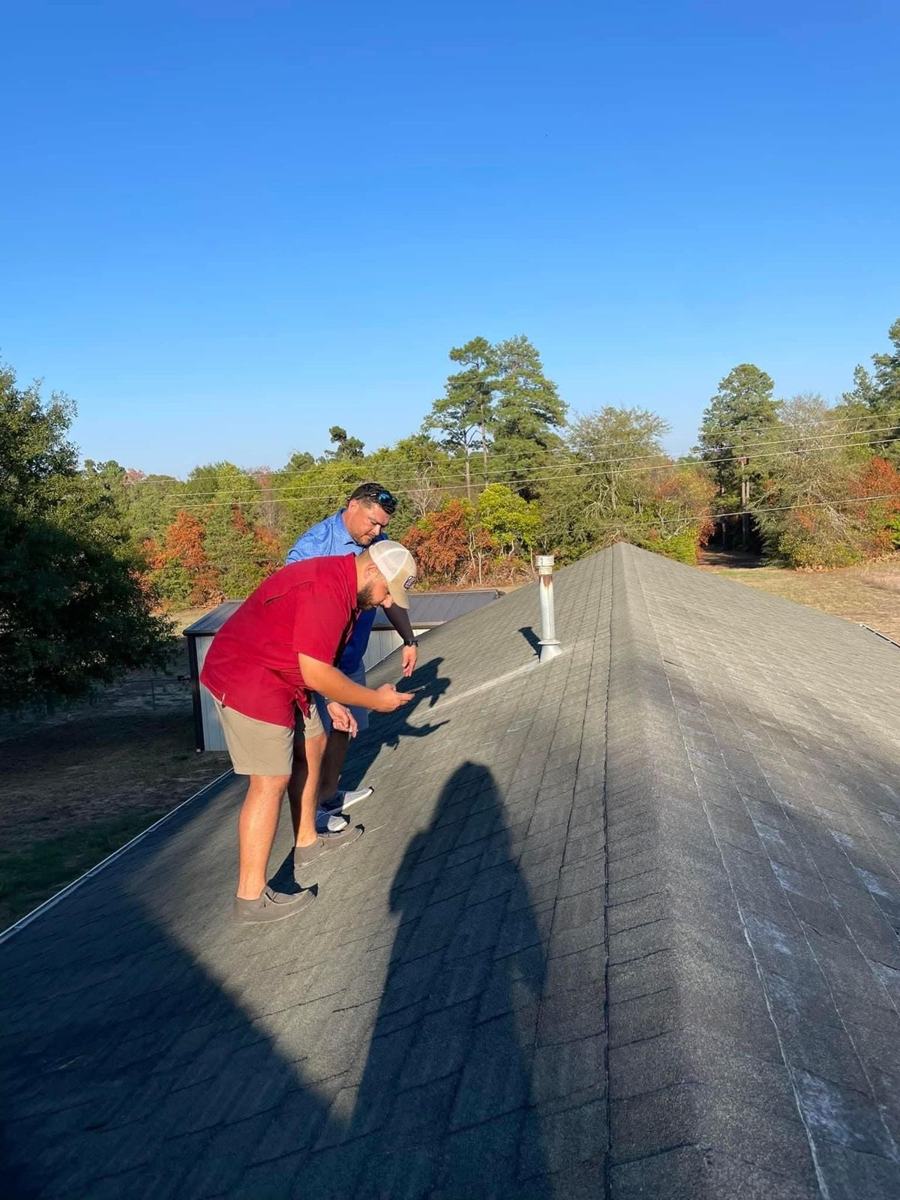
An Indemnity inspector meeting the insurance adjuster on the roof to walk through the storm damage together.
For the full step-by-step process, read our Louisiana Roof Insurance Claim Guide.
After a storm, you'll hear from a lot of roofers. Here's a checklist:
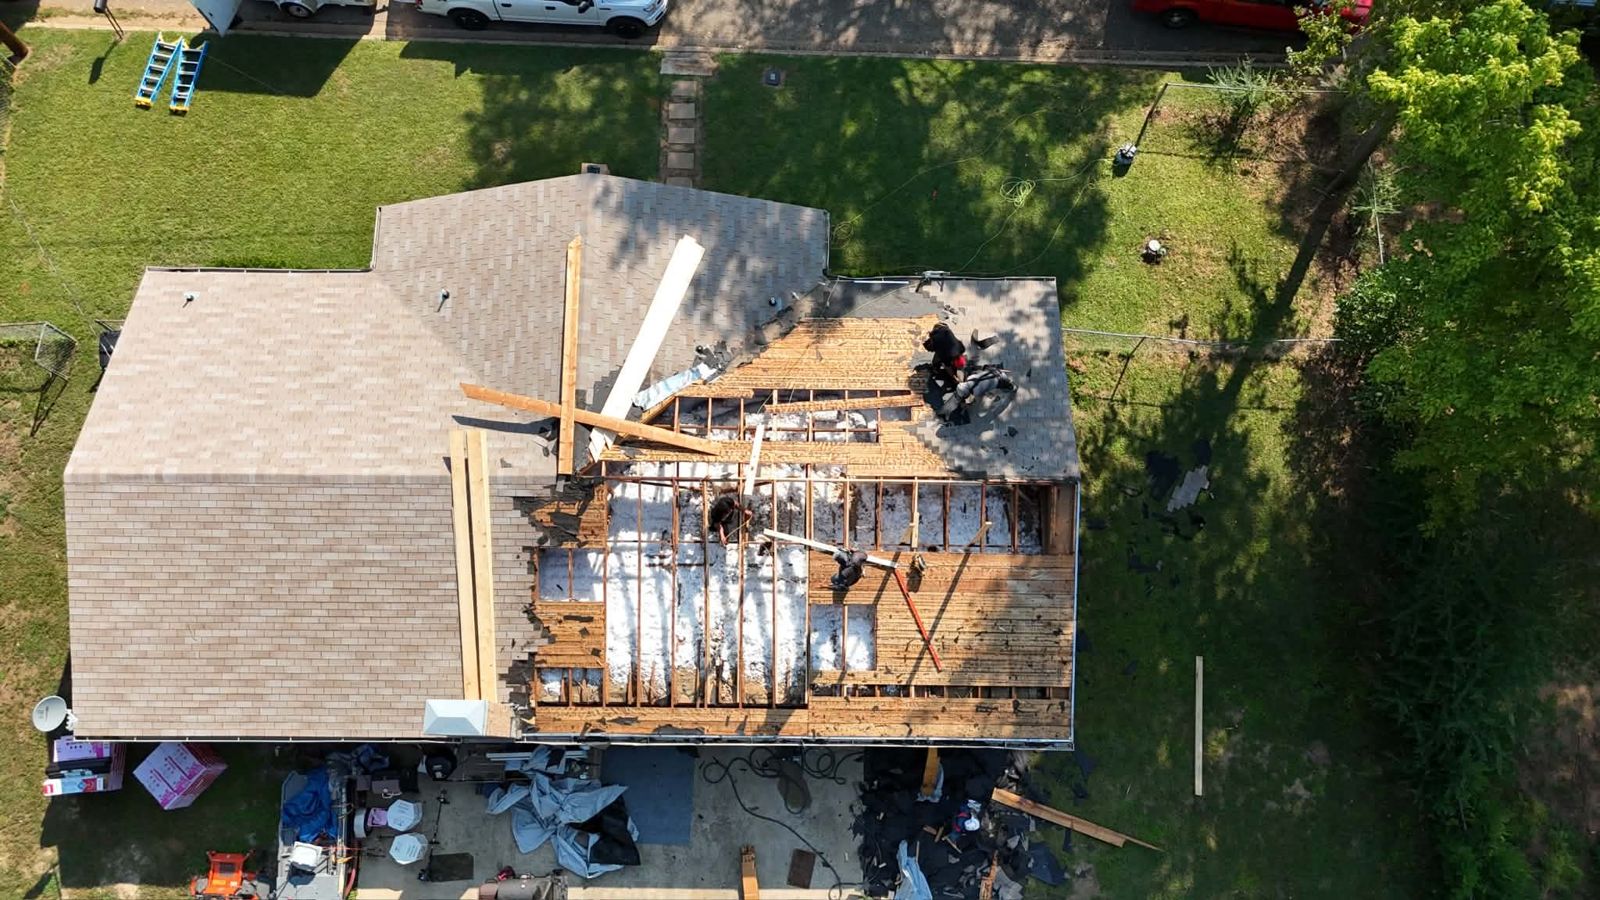
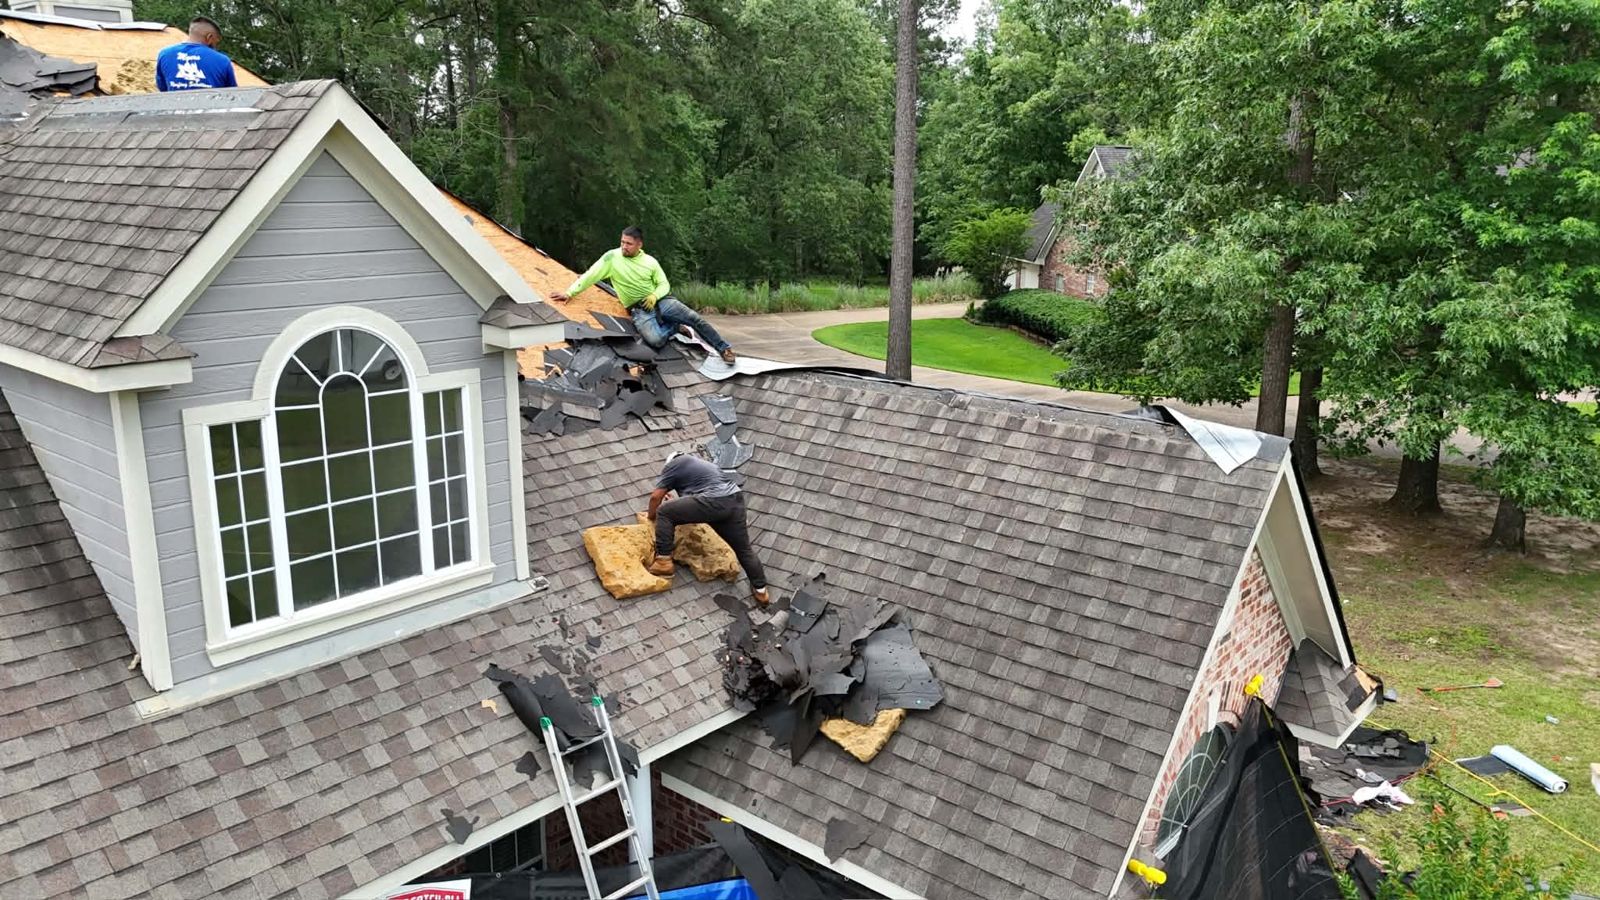
A full tear-off lets the crew inspect and repair the decking before the new roof goes on.


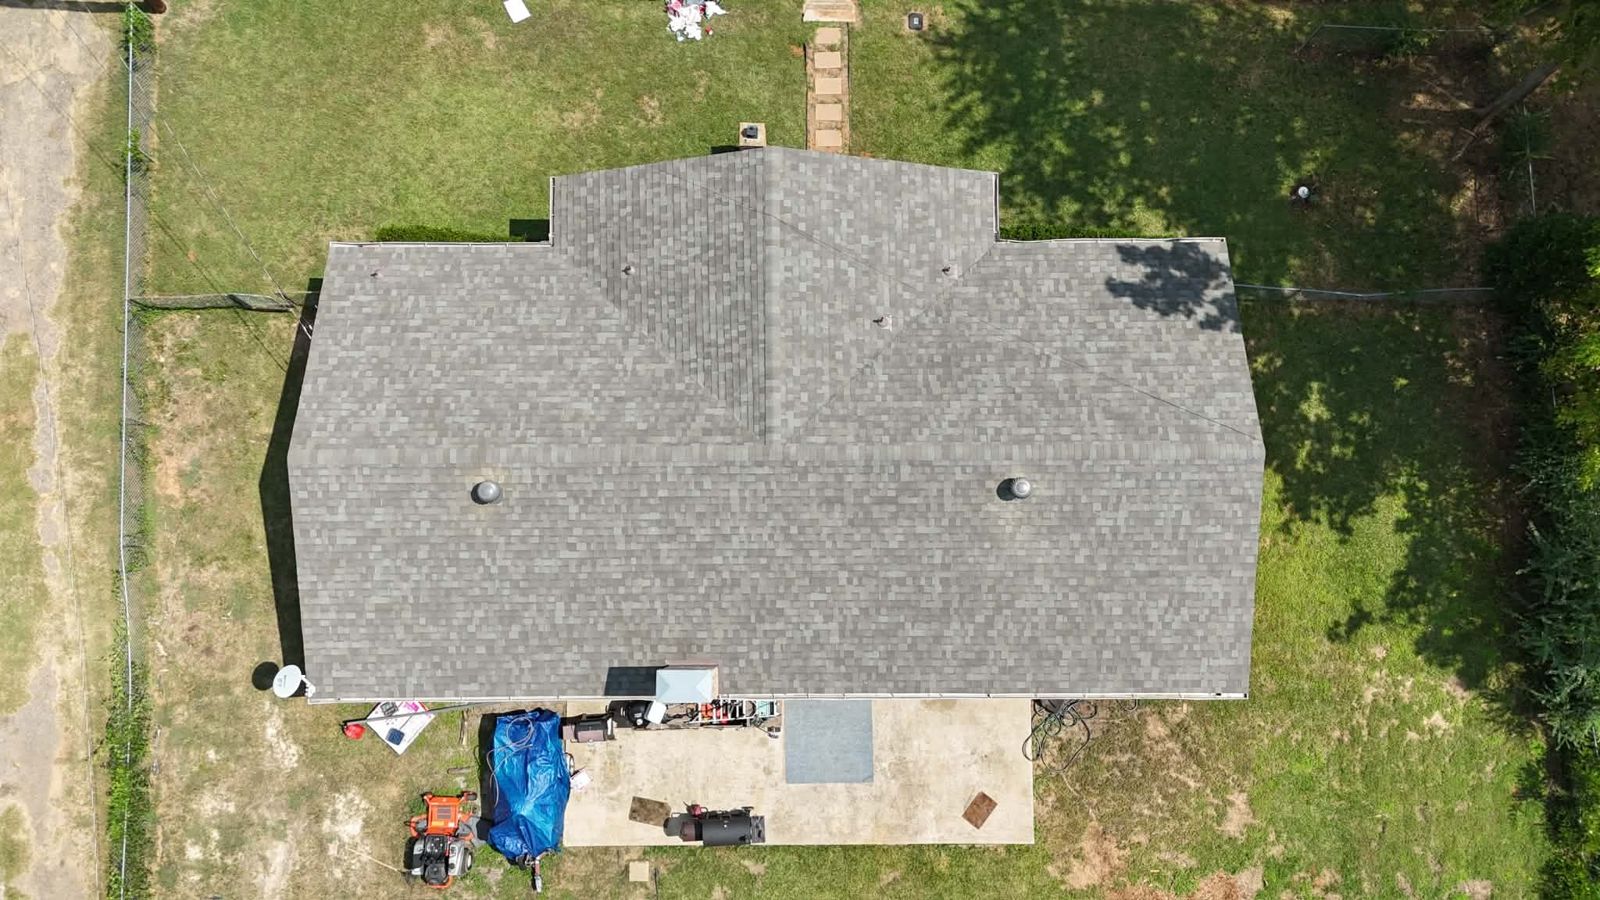
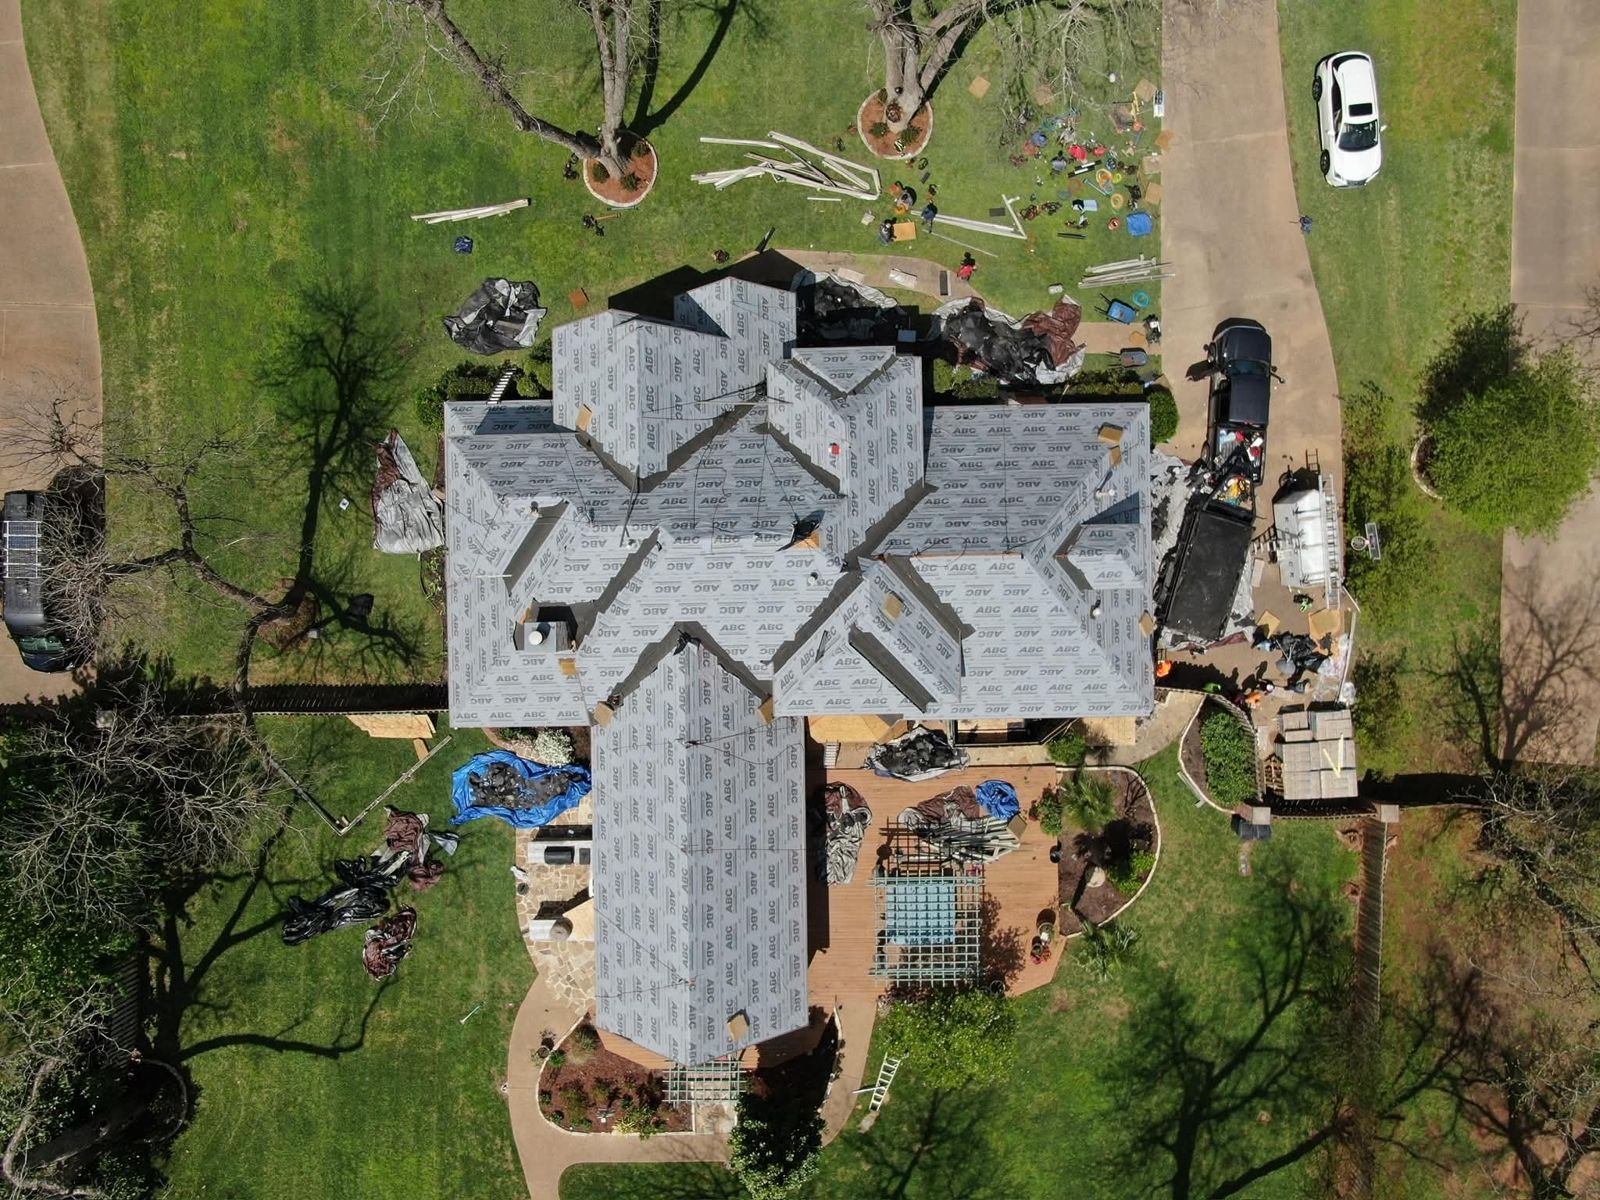
Mid-install with new underlayment on, and the finished roof.
We work with agents and contractors across Shreveport-Bossier and East Texas. We can:
Call (888) 334-9155 to set up an inspection for a client or a project.
Possibly, but policies have notice requirements and time limits. Check your policy or ask your insurance agent. A professional inspection can help show when and how the damage happened.
Generally, claims for damage that happened before you owned the home belong to the owner at the time of the storm. Talk with your agent about handling the roof before closing, such as a repair, replacement, or credit.
It depends on the roof's condition, the market, and whether there's storm damage. A pre-listing inspection shows where you stand so you can decide on repair, replacement, or pricing before a buyer's inspector finds it.
It can. Claims go on your insurance history and may affect future premiums or coverage, depending on your insurer. Ask your agent before filing, and get a free inspection first so you know whether there's real damage.
A roofer inspects and documents the damage, provides a repair estimate, meets the adjuster on site to show the damage, and does the work. A roofer shouldn't interpret your policy or negotiate the claim for you.
Ask for the decision in writing, request a re-inspection with your documentation, review your policy's dispute or appraisal process, and contact your state's Department of Insurance. You can also hire a licensed public adjuster or an attorney to represent you.
No. Waiving, rebating, or absorbing an insurance deductible is illegal in Louisiana, and you should avoid any contractor who offers it.
Indemnity Roofing's roof inspections are free, including a photo-documented report.
Whether you're living in the home, selling it, buying it, or working on it, start with the facts. Call (888) 334-9155 or request a free inspection online.
This guide is general information, not legal or insurance advice. Coverage depends on your specific policy. Consult your insurance agent, a licensed public adjuster, or an attorney about your situation.
Get a free, no-pressure roof inspection from a team that actually answers the phone.
Get My Free Inspection